
Let’s be honest. Most people do not skip travel because they do not want to go. They skip it because they are not sure how to pay for it without stress, guilt, or going into debt.
The good news is that saving for travel does not have to feel overwhelming or extreme. With a bit of intention and the right approach, even a “someday” trip can start to feel doable.
Here are four realistic ways to save for your travels, whether you are planning far ahead or just starting to think about what is next.
Get clear on what you’re saving for
Before you focus on how to save, take a few minutes to think about what you are saving for. You do not need exact numbers. Rough estimates are more than enough to get started.
Ask yourself:
-
Where do I want to go?
-
About how much might flights, lodging, food, and activities cost?
-
How long am I willing to save?
Even a ballpark number helps you choose a savings strategy that makes sense for your life and timeline.
1. Create a dedicated travel savings fund
One of the simplest and most effective ways to save for travel is to keep that money separate from your everyday spending.
This could be:
-
A physical cash jar: Better than nothing, but too easy to accidentally spend on non-travel expenses.
-
A dedicated travel bank account: My personal favorite strategy—keeping your travel fund in a separate account keeps it out of sight and out of mind until you’re ready to book.
When your travel money has its own place, you are less likely to spend it on something else. It is also incredibly motivating to watch that balance grow.
2. Automate your savings and keep it simple
Saving works best when it does not require constant decision-making. Setting up automated transfers—even for modest, consistent amounts—helps your travel fund grow without extra effort.
-
-
-
Weekly or biweekly: try setting aside a small amount from each paycheck
-
Monthly: schedule a transfer shortly after payday
-
-
The amount matters less than consistency. Saving $25 or $50 at a time may not feel exciting, but over a few months, it can cover flights, lodging, or a significant portion of your trip.
Boring savings is often the most successful savings.
3. Use rewards and cash back strategically
Cash back and travel rewards are an easy way to boost your travel fund without changing your daily spending habits.
I personally use Rakuten, which gives you cash back when you shop online at stores you already know and use. Instead of letting that money disappear, you can funnel it directly into your travel savings.
If you have an eligible American Express card, you can opt to earn AmEx Membership Rewards points instead of cash back. You can also pair this strategy with a Chase card to earn Unlimited Rewards points on your everyday purchases.
A few quick rules to keep in mind:
-
-
-
Treat rewards as a bonus, not your main savings strategy.
-
Pay off credit card balances in full each month to avoid interest fees.
-
Direct cash back straight into your travel account, and save your points intentionally for future flights or hotel stays.
-
-
4. Try the 52-Week Travel Savings Challenge
If you like structure or a clear plan, the 52-Week Savings Challenge can be a great option.
Here’s the basic idea:
-
-
-
Week 1: Save $1
-
Week 2: Save $2
-
Week 3: Save $3
-
Weeks 4-52: The weekly deposit amount continues to correspond with the week number.
-
-
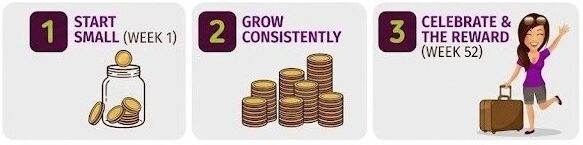
By the end of the year, you’ll have saved $1,378, which can go a long way toward your next trip.
You can also adjust the challenge to fit your life and savings style:
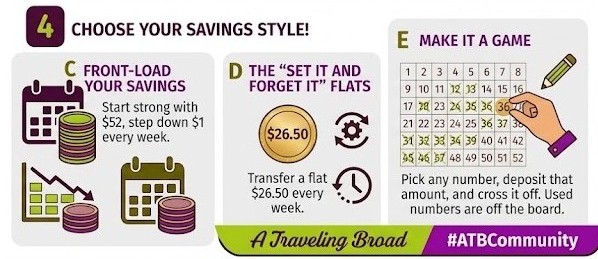
This approach works because it breaks a big goal into manageable steps. It is not about perfection. It is about building momentum.
A quick reminder before you go
You do not need unlimited money, a perfect budget, or a major lifestyle overhaul to travel more. You need a plan that works for you.
Whether your dream vacation is a weekend getaway or a bucket-list trip, these strategies help turn intention into action, one step at a time.
If you’re starting, that’s okay. Starting is often the most challenging part.
How are you saving for your next trip? Are you more of a set-it-and-forget-it saver, or do you love earning cash back and points? Drop a comment below and let me know!
*Disclosure: Some links in this post may be affiliate links. If you choose to use them, it helps support my work at no extra cost to you.
I’m pretty good at saving for vacations but when it comes to a splurge I specifically look for credit cards that have 0% interest and will apply for them. I always get them and use them for airline tickets and cruises. Since I book pretty far in advance I’m able to pay for those trips before we leave or at the very least have it paid for long before the promotional rate changes. I do love the cash back on a few of my cards. Secondly since we have a small dog that needs a sitter every time we shop for groceries I get $20-$40 cash back and this goes towards Daisy’s boarding fees, a cash option gets me a daily discount versus the Venmo or Zelle options. Looking forward to tips on saving on hotels.
Hey Amy, that is great advice! I’ve never heard of the 52 week challenge before this! I will have to start doing this too. One thing that I already do that really helps me put money away is pay myself first. When any money comes in, I put at least 10% of it away into a ‘financial freedom’ account. Paying yourself first instead of your bill(still pay your bills of course), lets the universe know that you consider yourself more important than bills-it’s an ‘energy’ thing. Can’t wait to hear more from you! Great posts so far!
Hi, Jane. Thanks for reading my post and commenting. I, too, have money taken out of my paycheck and “pay myself first.” I didn’t start doing this until later in my life, but its never too late to start. Its great to see the savings and 401(k) balances increasing – it keeps me motivated to continue saving. 🙂
These savings tips are simple enough to do. I think most people might want to take more aggressive savings steps and change the numbers to suit their goal. Let’s say I want to get up to the point where I’m saving 20% of my income. Then I need to figure out what 20% of my weekly earnings is and make that Week 52, then work backward from there. Example: I make $1,000 a week. Week 52 deposit is $200. Divide 52 into 200 and it’s roughly 4. So make the increments each week jump by $4. Week 1 = $4, Week 2 = $8, Week 10 = $40, and so on.
Yes, Tracey, I agree that many people will want to save more money than $1,378. However, the plan options offer ideas for starting to save, which is the ultimate goal. Thanks for the comment!